James Marks: The AWS Insider Who Saw a $500B Inefficiency
Key points: Said at the table.
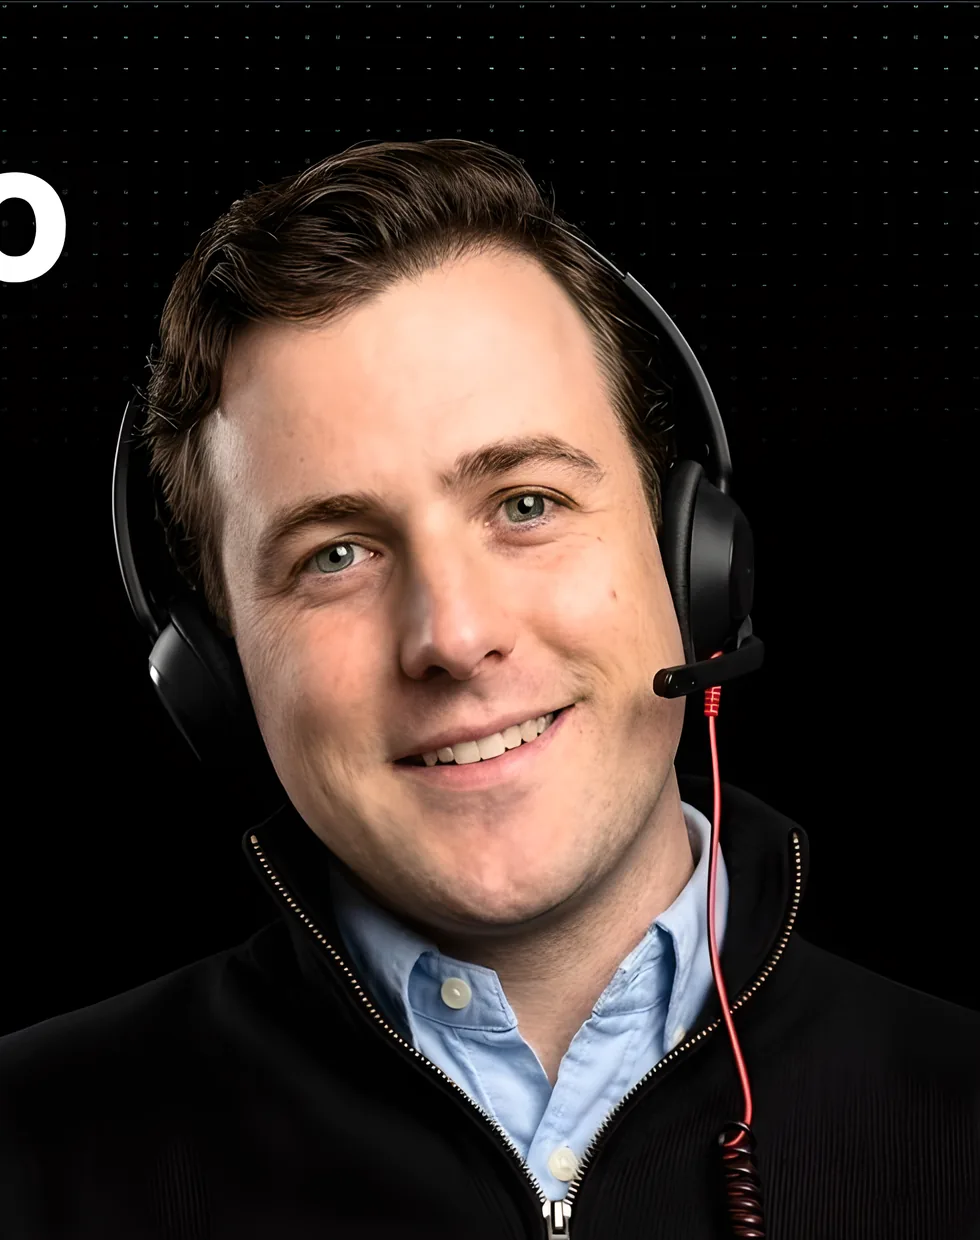
Who is James Marks?
James Marks is the founder and CEO of Canopy, a cloud and IT infrastructure broker that acts as a growth partner on a company's cloud strategy. He joined Amazon as a graduate, had seven jobs in seven years there, and then left AWS to start Canopy.
- 7jobs in seven years at Amazon, before he left to start Canopy13:47
- 26his age when he led a team across Europe at Amazon, by his own account12:53
- 3 to 4months after launch that Canopy closed a deal with a publicly listed company18:50
- Early on
Picks tech over banking and joins Amazon as a graduate
12:23 - At 26
Leads a team across Europe at Amazon
12:53 - Later
Moves into AWS's global productivity team and sees the scale of its deals
13:05 - Leaving
Quits AWS to build his own business
13:56 - Today
Founder and CEO of Canopy, a cloud and IT infrastructure broker
0:42
What Does a Cloud Broker Do? Notes From Canopy's Founder
What does a cloud broker do? James Marks, founder and CEO of Canopy, says it acts as a growth partner on a company's cloud strategy: it passes market knowledge on to the customer and works as an extension of its IT procurement and finance teams. He left seven years at Amazon and AWS to build one.
Host Niclas Schlopsna opens by asking whether it can slash cloud bills by 20 to 40 percent. James answers with one customer analysis at 30 percent and a mention of case studies, and the later part of the episode covers how he raised his pre-seed round on a monthly investor memo.
What does a cloud broker do for a company?
A cloud broker, also called a cloud service broker, is what James runs at Canopy, which was just over a year old when the episode was recorded. His own label for it is a cloud and IT infrastructure broker.
The market keeps shifting, he says: new players keep entering, and customers get access to different funding and incentives at different stages. Canopy is "effectively an aggregator of all that really good knowledge" that it passes on to the customer.
Canopy works on multi-million dollar commercial contracts, and some of its clients spend over 25 million a year on cloud.
He also calls Canopy an extension of IT procurement and finance, which brings together two teams that "at the best of times don't like talking to each other." On three-year deals AI helps, and Canopy uses such tools internally, but it still takes a person with the CTOs and CFOs to get a deal over the line.
A large part of the money Canopy raised goes into a self-serve platform meant to put an expert negotiator and broker for cloud infrastructure in the customer's pocket.
Why do companies buy through a broker?
James makes the case with an analogy from home loans. About 10 percent of mortgages were once signed with a mortgage broker, in his telling. Everyone went directly to the bank and knew the bank manager.
Today over 95 percent are, because there are 30 different providers with 30 different products and you trust your broker to get you the best deal.
James Marks on Deal Makers (& Fakers), at 9:55
He applies the same logic to cloud. Technology teams do their best work building products, and Canopy takes on the talking to the cloud providers' sales teams as an extension of the customer's team: "you've got to play to your strengths."
The analogy has a limit, which he names himself: at some point the deals get so big that going direct to the provider can be the best route.
Can a cloud broker deliver cloud cost savings of 20 to 40 percent?
The 20 to 40 percent range is the host's wording from the introduction. James answers yes and says Canopy has example case studies to prove it, though he names none on air. He adds that cloud cost savings are a byproduct of the work and that the main point is increasing value.
The one saving figure he gives comes from a call he had that morning, analyzing a customer.
“As a conservative number, we went back to the customer with 30%.”
That 30 percent sits inside the range, but it was put to one customer under analysis, and the episode shows no measured result: no baseline for it, no split across the layers he names next, and no tactics for cloud cost optimization or cloud cost management.
The episode also leaves out how Canopy charges for its cloud broker services, what its contracts bind a customer to beyond a mention of three-year deals, and how a customer would leave one.
There are different layers to the saving, he says: commercial, architectural and cost optimization in terms of governance and how the spend is managed. Large institutions run massive teams to manage this, and FinOps as an industry has emerged because of the inefficiency, particularly at mid-market and larger enterprise clients.
In his estimate, a trillion dollar cloud market is, generously, about 50 percent efficient, and the waste comes to four to five hundred billion dollars a year. He gives two reasons cloud spend matters to a company:
- AI natives raising 10 to 20 million. Almost half of it, if not more, goes to cloud infrastructure, he says, especially for those training their own models.
- Companies building AI products. With two companies building the same AI product and one doing it at half the price, the cheaper one gets further along the roadmap, and cloud cost becomes a competitive advantage.
How does a cloud insider become a cloud broker founder?
James chose tech over banking and finance early on and joined Amazon as a graduate. Back then, he says, it was effectively the world's biggest startup and the best place to learn entrepreneurship.
He rose quickly: at 26 he had a team across Europe, and a move into a global productivity team showed him the scale, with AWS a 90 odd billion dollar run rate business at that point. He had seven jobs in seven years at Amazon, and says he learns quickly and gets bored quickly.
Leaving became an "if not now, when" moment in which the worst case was moving back into a role.
He expected maybe 10 other people around the world to have the same idea, so the question was how fast he could become a first mover. Cloud and IT infrastructure brokers existed a while ago and now barely exist outside a big four consultancy, he says.
Why was a cloud broker hard for investors to back?
James needed funding the moment he left Amazon. As a cloud broker, Canopy sells high-ticket enterprise deals, and without the AWS brand behind him everyone asked who it was. Credibility and partnerships take time to build, so the company needed investment as a buffer.
For the stage in general, there is a guide to how a pre-seed round works.
Canopy signed its first blue chip deal 3 to 4 months after launching, with a publicly listed company that had never used a consultancy outside the big four. It didn't yet have the whole revenue to show for it, he says, but it was clearly in the right space.
The round had enough market signal, but the way there was not easy. He hit about three investment committees, and a lot of VCs, with all due respect, didn't understand much of what Canopy was doing.
“Cloud brokers and IT infrastructure brokers don't really exist, right? There are SaaS management platforms, but we're in a very, very small niche.”
When he started, he says, maybe 400 people in the world knew what was going on, and 398 of them still sat in well-paid jobs at American businesses. His law firm had never drafted a contract like his.
James calls creating something that doesn't exist in the market the biggest challenge, and says investors have to take a real risk on an individual solo founder. Jessica Liew, another pre-seed founder on the show, took a different route: one of her larger investors came from targeted cold outreach.
Do monthly investor updates work for a pre-seed raise?
James ran his raise on a monthly memo to investors. Each month he wrote one memo of 3 or 4 pages that said where the company stood, and put investors and people from his community on a mailing list, because he had no time to jump on 20 calls with 20 people to give updates.
Host Niclas Schlopsna, who met James in Helsinki at Slush, where James pitched him the business, landed on that list afterwards and says the updates impressed him.
- Step 1: Start a mailing list
Investors and people from his community go on it, so he does not need 20 calls with 20 people.
22:37 - Step 4: Send newcomers the last three memos
Anyone who gets in touch reads them before any meeting: "it's all there in black and white."
23:31 - Step 5: Take a chat only if they are serious
The reading comes first; a conversation follows only if the investor is serious.
23:46 - Step 6: Update the whole group after each ticket
Every time a ticket comes in, everyone on the list hears about it.
23:52
James Marks on Deal Makers (& Fakers), 22:37 to 25:00
About 6 weeks after he started, the first tickets, the investors' cheques, began to roll in. Investors could see the progress from one month to the next, he says, and "numbers speak for themselves".
Anyone who got in touch was sent the last three investor memos to read before any meeting, and James's message to them was blunt:
“Do your work, right? Because you're not going to waste my time unless you're serious about this. Have a read, it's all there in black and white.”
By his account the round closed around Christmas Eve, with a ticket on Monday, one on Tuesday and two on the Thursday, though earlier in the episode he calls it recently pre-closed. He compares the memo to sales: keep investors warm like leads, and when they see the jump in ARR projection, pipeline and signed deals, that is something they want to invest in.
James automated the whole report with AI. HubSpot and partnership activity feed it, he writes the executive summary by hand, and the memo takes him about an hour a month. The host estimates that hour saves around 10 hours of meetings with individual investors.
Florian Myter did the same on a different clock, an update every two weeks or every month, and says regular investor updates helped raise his pre-seed round.
Do you need a pitch deck to raise money?
The host asks what James wishes he had known before fundraising, and his answer opens with one instruction.
“Spend zero time on your decks. Honestly, spend zero time on your decks.”
Spend all your time trying to win customers, he adds. Go to an investor later on with 500k of revenue and, in his words, you don't need a deck: they say they will invest.
A lot of very successful companies, he says, put their initial decks together in 2 minutes. A deck can also be a bit of a power play, in his view, and it is just numbers on a spreadsheet on a slide while the real business is far bigger.
What investors need, as he sees it, is a vision of a billion dollar business, and you have to tell them how the company will win enterprise clients and what it can save them.
Kirk Donohoe makes a related point about a first investor call: it was informal, and he says going in with a structured pitch deck ready to speak for 20 minutes loses the investor's interest.
What should a first-time founder know before the next round?
James's own advice is to pick the kind of investment you are looking for, because it can open doors and other incentives, and to only raise when you have to.
This was his first raise, so it is hard to tell yet what he has learned. In his view investors can be at their most painful on exit and on decisions about future funding rounds. He adds that Canopy will be raising capital very soon if the stars align.
A founder can take three things from his route: raise only when you have to, keep investors warm with a monthly memo of 3 or 4 pages, and put the time a deck would take into winning customers.
For a company weighing a cloud broker, the number to test is the conservative figure he took back to a customer: he says case studies exist, and the episode shows none.
Asked and answered.
5 questions this conversation answers, in plain words.
A cloud broker is also called a cloud service broker. James Marks describes it as an aggregator of market knowledge: it follows new players, funding and incentives and passes them on to the customer. He also calls Canopy an extension of a company's IT procurement and finance teams.
Canopy, the company James Marks founded, is one. He says few cloud and IT infrastructure brokers exist now and that they barely exist outside a big four consultancy.
James says savings come in layers: commercial, architectural and cost optimization in terms of governance. Large institutions run massive teams to manage this. On one customer analysis, Canopy went back with 30% as a conservative number. The episode names no technical tactics for cloud cost optimization or cloud cost management.
James says the cost inefficiency shows up particularly at mid-market and larger enterprise clients, and that some of Canopy's clients spend over 25 million a year on cloud. He also cites AI companies that put almost half, if not more, of a 10 to 20 million raise into cloud infrastructure. He offers no guidance for small companies, and says that at some deal size going direct to the provider can be the best route.
James sent his monthly, a memo of three or four pages, and updated the whole group after every ticket that came in. He says there is no right or wrong answer, and that with automation the monthly memo takes him about an hour.
Meet James at Canopy, or keep listening.
One thing the host asks of investors on air, and two ways to carry on.
- For investorsGet in touch with James
Niclas Schlopsna says that any VC or family office interested in meeting James will find his contact details in the episode description.
Said at 29:16Visit Canopy - Keep listeningA pre-seed founder who used cold outreach
Jessica Liew raised a pre-seed round and found one of her larger investors through targeted cold outreach, a different route from James's memos.
Listen to Jessica Liew - The showFollow Deal Makers (& Fakers)
Follow the show so you don't miss the next deal story.
Follow on Spotify